

An interview with Vanessa Dager,
Head of Advisory North America, BNP Paribas.
Supported by large strategic transactions, AI-driven investment and growing cross-border M&A activity between the US and Europe, the US M&A market has been strong in the first nine months of 2026. In this US M&A market review, Vanessa Dager, Head of Advisory North America at BNP Paribas, discusses why megadeals1 have shaped overall US M&A volumes, how corporate and private equity strategies are evolving, and what interest-rate uncertainty could mean for the US M&A outlook for 2027.
Key takeaways
- Megadeals have defined the 2026 US M&A market to date. M&A deal value increased by 38% year on year in the first nine months of 2026, with megadeals – transactions greater than USD10 billion – accounting for approximately 48% of year-to-date deal value.
- AI and technology investment is driving US M&A activity across sectors. Its impact extends beyond technology to energy, infrastructure, industrials and healthcare, as companies acquire the capabilities and infrastructure needed to support AI development.
- Cross-border M&A between the US and Europe is accelerating, reaching its strongest level in two decades. Europe represents approximately 67% of US outbound M&A deal value, while European buyers continue to pursue opportunities in the US for its scale, resilience, technology leadership and innovation ecosystem.
What is driving US M&A activity in 2026?
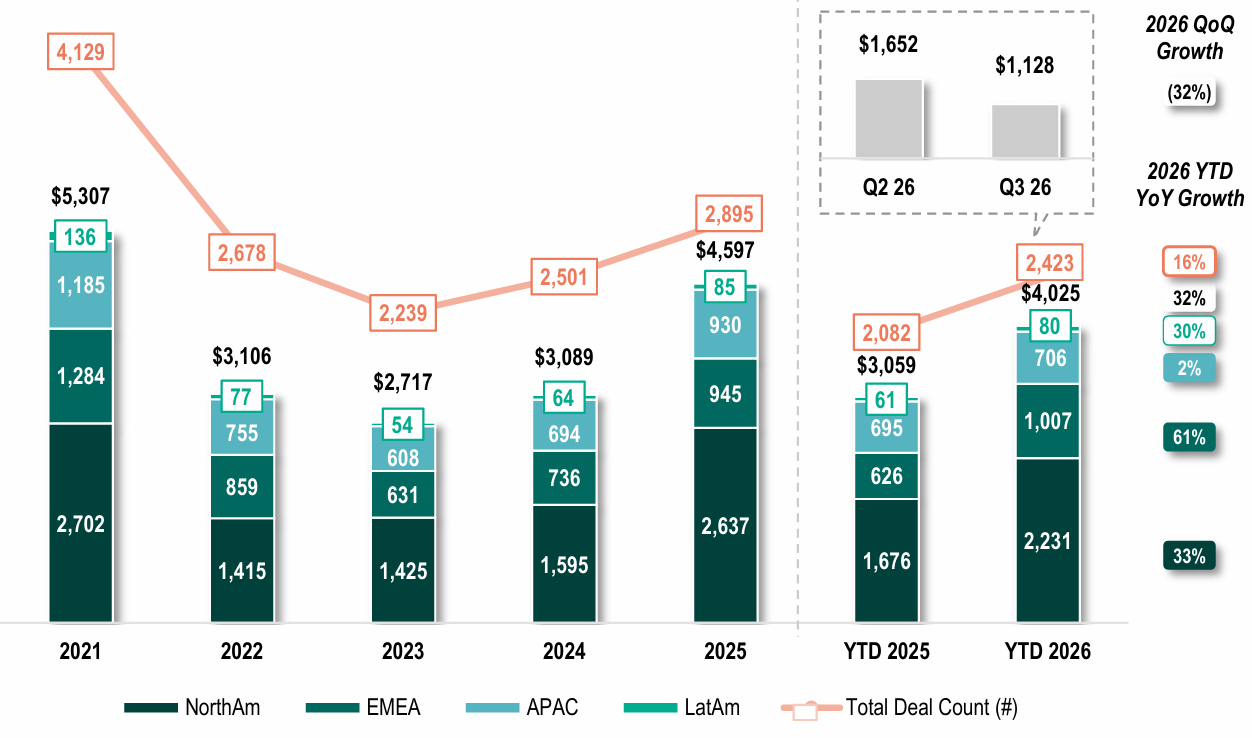
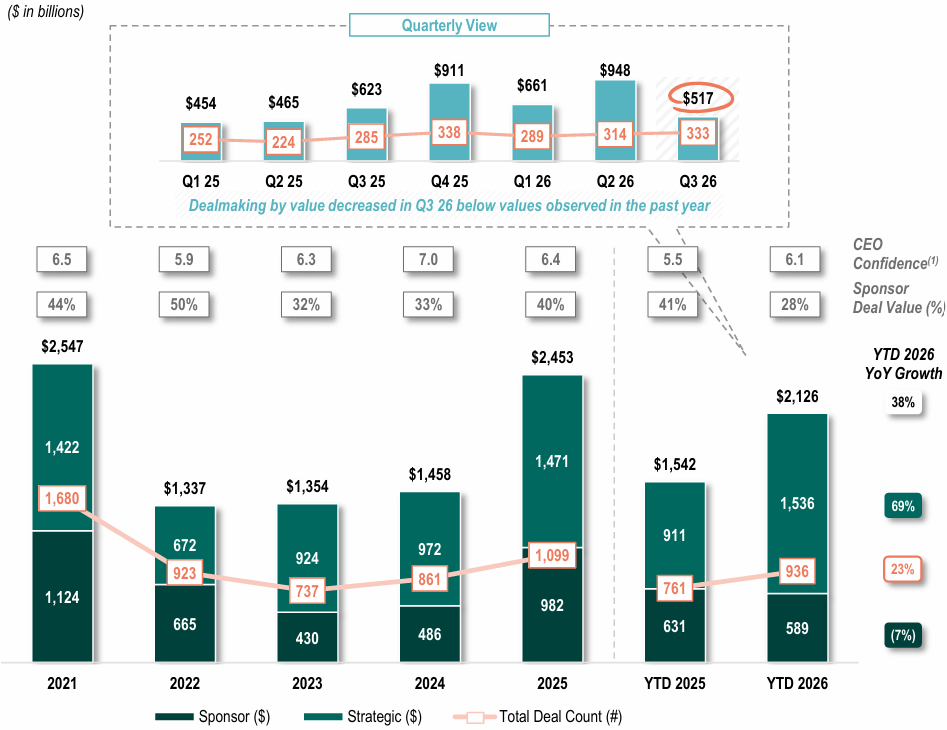
It has been a strong year for the US M&A market. Year to date, overall US M&A deal value is up 38% with deal count up 23%, both year on year. The defining characteristic of the market has been the strong increase in megadeals, with a record 34 megadeals accounting for nearly half of deal value through Q3 2026.
This strength is part of a broader M&A trend: global M&A value is up approximately 32% year on year, marking a third consecutive year of expansion, with North America accounting for more than half of global deal value.
The first half of the year was particularly strong, including a very active summer. However, we have seen a slowdown in Q3 2026 that can be correlated to volatility around interest rates and AI.
Global M&A deal count and value evolution (by region1, USD in billions)
Source: Dealogic as of 30 September 2026, S&P Global Market Intelligence, Capital IQ, Reuters, PwC; Note: Analysis based on announced transactions equal to or greater than USD200m in value; (1) Based on target’s primary nationality
Which sectors have been driving US M&A activity in 2026?
❝ The ten largest US M&A deals year to date are almost entirely in TMT and energy, with corporates driving the megadeal cohort. ❞
AI is the structural driver of M&A, reflected in the growth of M&A activity in TMT (Technology, Media and Telecommunications), which reached USD763 billion year to date, up 27% year on year. AI is also influencing capital deployment across energy, infrastructure, industrials and healthcare, including the investment needed to build data centres and the wider infrastructure supporting AI.
Energy deal value increased 53% year on year to USD341 billion, driven by corporates adding electricity and data-centre capacity. Corporate capital is also rotating towards defence and aerospace, cybersecurity, sovereign AI infrastructure and utilities powering AI.
Together, TMT and energy account for approximately half of US M&A market growth, with healthcare emerging as a third strong engine of activity – deal value up 89% year on year – largely driven by portfolio considerations, as pharmaceutical companies secure future pipelines and growth.
Why is cross-border M&A activity between the US and Europe so strong?
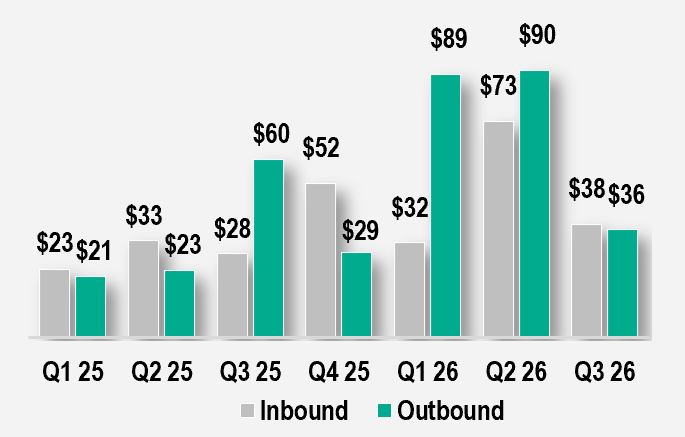
The US-Europe cross-border M&A corridor is dominating the market, accounting for 60% of all US cross-border activity. Total US-Europe transatlantic M&A activity reached USD360 billion in the first nine months of 2026, nearly twice the level recorded over the same period a year earlier. This trend is particularly relevant for us at BNP Paribas, given our strong presence and expertise in both the US and Europe and our ability to support clients as they pursue strategic opportunities in both directions across the transatlantic corridor.
Transatlantic deal value (USD in billions)
Source: Dealogic as of 30 September 2026, Capital IQ, Bloomberg, Mergermarket; Notes: Analysis based on announced transactions equal to or greater than USD200m in value
Because of its tech leadership, innovation ecosystem and scale, the US market continues to be an attractive destination for European companies looking to strengthen their strategic positioning and access in this space, while a weaker US dollar has given European buyers an attractive entry point.
We are also seeing significant cross-border M&A activity in healthcare and industrial sectors as European companies look to acquire a local presence in the US or expand their existing footprint. A great example, this year, is the US acquisition by a larger privately held Italian pharmaceuticals company. It was their first major acquisition in the US market and BNP Paribas supported the transaction with advisory, financing and hedging.
❝ This particular acquisition is a good illustration of how European companies are using M&A to access growth opportunities, innovation and scale in the US. As clients seek to expand their geographic and product footprint, they increasingly value a banking partner with deep expertise on both sides of the transatlantic corridor, global reach and an integrated model capable of supporting their strategic ambitions across markets. ❞
What is driving corporate strategic M&A interest?
US corporates continue to show strong performance and healthy balance sheets and leverage levels, while continuing to take a long-term view despite heightened geopolitical and macroeconomic uncertainty. While the US M&A market has adapted to a higher-rate environment and the Federal Reserve’s restrictive monetary policy is expected to continue into 2027, strategic buyers have a variety of financing options, including the use of stock. They are pursuing transformational transactions, acquisitions that create scale, and combinations that are designed to deliver synergies and value for shareholders over the long term.
❝ The largest deals are primarily strategic. Corporates are looking to acquire scale, capabilities and opportunities for long-term growth. ❞
Valuation levels in AI-adjacent sectors, such as services, energy and digital infrastructure, remain high, yet transactions are continuing to take place as record levels of capital are being raised across equity and debt markets. While this is creating a more crowded market for other corporate borrowers, we have not seen this prevent companies in other sectors from pursuing M&A, notably within healthcare.
US M&A deal count and value evolution (USD in billions)
Source: Dealogic as of 30 September 2026, Bloomberg; PwC; Notes: Analysis based on announced transactions equal to or greater than USD200m in value; US M&A activity refers to deals including targets with primary nationality in the US; (1) CEO Confidence Index, as of 31 August 2026
What role are private equity sponsors playing in the US M&A market?
Q3 2026 saw sponsors re-engage and activity during the quarter was strong, with USD271 billion in deal value across 106 deals. However, compared to 2025 when sponsors represented 40% of overall M&A deal value, the first nine months of 2026 have seen this decline to approximately 28%, despite near-record pent-up sponsor firepower of approximately USD2.5 trillion. The cost of capital remains the main constraint, with smaller and mid-market firms facing the greatest challenges. Average holding periods are longer, and sponsors continue to look for alternative liquidity mechanisms, including the use of continuation funds.
What is the US M&A outlook through the end of 2026 and into 2027?
The US M&A market remains resilient, and many of the structural tailwinds we have seen in the first nine months of 2026 should continue into the end of the year and into 2027. Management teams continue to take the long view, pursuing both transformational transactions and bolt-on acquisitions. US-Europe cross-border M&A is at its strongest in two decades. Deal activity through the transatlantic corridor is expected to continue to dominate, driven by structural demand for AI and generative AI infrastructure, including data centres, AI electricity supply, and the pipeline needs of larger pharmaceutical companies.
However, while initial signs of a cool-down emerged in Q3, and will need to be monitored as we move into Q4, a sense of cautious optimism remains. AI, innovation and cross-border corporate investment will continue to support corporate M&A activity domestically as well as internationally, while rates, energy prices and the pace of sponsor recovery remain important watchpoints.
[1] Transactions greater than USD10 billion
All figures referred to in the above text are sourced from BNP Paribas, Dealogic, and as at 30 September 2026, and based on announced transactions equal to or greater than USD200 million in value.
This material is for informational purposes only and is not intended to be a complete and full description of the products of BNP Paribas and its affiliates or the risks they involve. Additional information is available upon request. Neither the information nor any opinion contained in this material constitutes a recommendation, solicitation or offer by BNP Paribas or its affiliates to buy or sell any security, futures contract, options contract, derivative instrument, financial instrument, or service, nor shall it be deemed to provide investment, tax, legal, accounting or other advice. All opinions, information, and estimates in this material constitute BNP Paribas’ or its affiliates’ judgment as of the date of this material. This material is only intended to generate discussions regarding particular instruments and financing and/or investments opportunities and is subject to change, or may be discontinued, without notice. This is not a research report nor is it prepared by BNP Paribas’ Research Department. This material should neither be regarded as comprehensive nor sufficient for making financing and/or investment decisions, nor should it be used in place of professional advice. You should consult your own advisors about any products or services described herein in order to evaluate the merits, suitability, and financial, legal, regulatory, accounting and tax issues raised by any investment and should not rely on BNP Paribas or its affiliates for this. Information contained herein is derived from sources generally believed to be reliable, but no warranty is made that such information is accurate, complete or fair and should not be relied on as such. The offer and sale of securities to institutional investors may only be made through the US registered broker dealer and futures commission merchant entity, BNP Paribas Securities Corp.


